Bank Holds: Available Balance vs. Current Balance
Bank holds can make money appear in your account before you can spend it.
Bank holds can make money appear in your account before you can spend it.
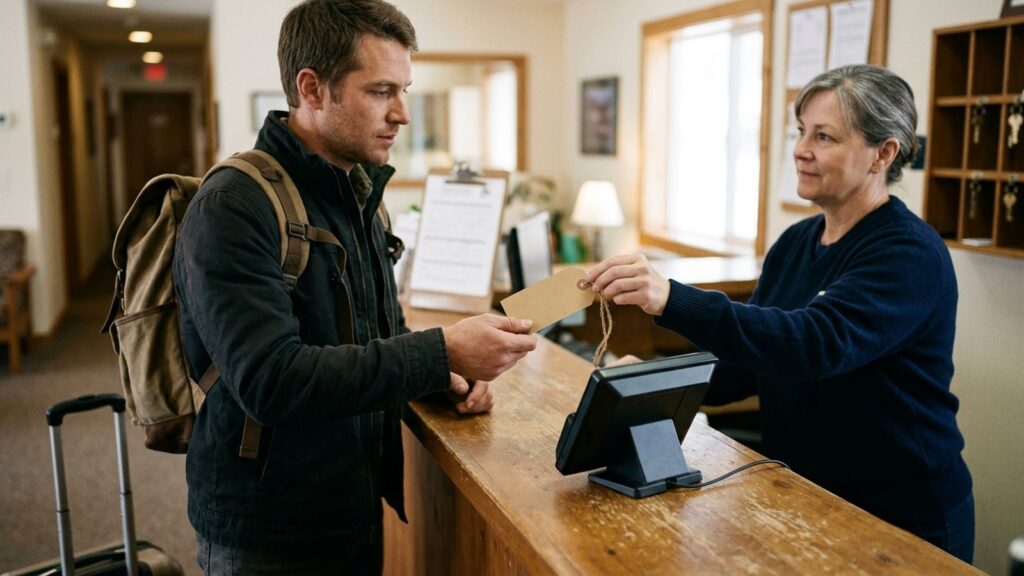
You deposit a check, see the balance rise, and schedule a bill payment. Later, the payment fails because the deposit was not yet available. The apparent contradiction comes from looking at a record of account activity as though it were a promise that every dollar could leave immediately.
Balance labels vary by institution. A current or ledger balance generally reflects posted transactions, while an available balance usually adjusts for certain holds and pending activity. Read your bank’s definitions rather than assuming its app uses those words exactly like another bank. Neither figure replaces a record of payments you have already authorized.
First identify what kind of hold you have
A deposit hold delays access to some or all of incoming funds. A debit card authorization hold reserves money for an expected outgoing transaction. Both can reduce what you can use, but they have different causes, documents, and release processes. Calling either one a frozen account can send the conversation in the wrong direction.
For a deposited check, find the receipt or availability notice and identify the amount held. Ask when each portion becomes available and whether the date assumes ordinary business-day processing. For a card transaction, identify the merchant, authorization amount, and whether the final charge has already posted.
The FDIC’s checking account management guide explains that authorization holds can reduce available money and that online balances may not yet reflect every transaction. It also recommends tracking future automatic payments. These are separate reasons why a displayed balance can exceed the money safely available for a new purchase.
Reconcile the balances before moving money
Imagine a hypothetical current balance that includes a newly posted check, but part of that deposit is held. The available balance may exclude the held portion and also reserve money for a pending card authorization. The difference between the balances therefore does not automatically equal the deposit hold.
Open the transaction details rather than subtracting two headline figures and guessing. Check for posted deposits, pending deposits, card authorizations, fees, and any account-specific restrictions. Ask whether an overdraft line or other linked credit is included in a displayed figure; borrowed capacity is not the same as your own cleared cash.
Then subtract commitments the bank may not yet see: checks you wrote, an automatic payment due tomorrow, or a debit card tip that has not settled. Do not count the same pending transaction twice. A small transaction register can distinguish what the bank already deducted from what remains only in your own records.
Deposit timing depends on more than the day you visited
The deposit method matters. A deposit made in person, at an ATM, or by mobile app can be subject to different processing rules and disclosures. Ask which funds-availability policy applies to the method actually used. A mobile deposit confirmation proves receipt of the submission, not necessarily final acceptance or immediate availability.
Cutoff times also matter. A deposit submitted after the institution’s cutoff may be treated as received on the next banking day. Weekends and federal holidays can extend the calendar wait even when a policy describes a short number of business days. Ask for a specific date rather than translating business days in your head.
Do not rely on an old chart copied from another website. The CFPB’s Regulation CC threshold notice lists inflation-adjusted amounts effective July 1, 2025, including a $275 minimum amount and a $6,725 large-deposit threshold. Those figures are parts of a broader rule, not a promise that every kind of deposit must be released on the same schedule.
New-account rules, exception holds, the type of check, and other circumstances can affect availability. Request the reason and applicable notice for your particular deposit instead of assuming the general schedule resolves it. If a bank representative cites a different threshold, ask which rule and effective date they are using.
A merchant hold needs a different conversation
A hotel, rental car company, or fuel merchant may authorize an amount before the final cost is known. The authorization can temporarily reduce available funds even though the final purchase has not posted. The FDIC guide specifically identifies these kinds of debit card holds as something account holders should monitor.
If the final transaction posts while a related authorization remains visible, ask the bank whether it is temporarily reserving funds for the same purchase. Keep the merchant receipt and cancellation or checkout confirmation. The merchant may need to send a reversal, while the bank can explain its own release process.
A merchant saying it released a hold does not establish when the available balance will update. Ask for the expected timing and a reference if available. If you do not recognize the transaction, report it promptly through the bank’s official fraud channel rather than waiting for the authorization to disappear.
Ask questions that produce an actionable answer
- Which transaction caused the restriction, and what amount is unavailable?
- Is this a deposit hold, card authorization, or another account restriction?
- What is the release date for each portion, and what could change it?
- Does the displayed available balance include linked credit or exclude any pending activity?
- Where can I obtain the applicable policy or written notice?
Record the date, representative or case reference, and explanation. If the notice and online display disagree, send both through a verified channel and ask the institution to reconcile them. A screenshot can preserve what you saw, but protect account numbers when sharing it and never send banking credentials to an unsolicited contact.
If a payment is about to leave, address that timing separately. Contact the payee before the due date to discuss legitimate options, and ask the bank about any fee consequences. An expected release is not a reason to assume a payment will clear earlier than the bank confirms.
Available does not always mean finally collected
A particularly important distinction is between access to funds and final payment of the underlying check. A bank can make a deposit available before it discovers a problem with the check. Do not send money back to a stranger simply because the deposit appears spendable; availability alone does not validate the transaction.
For ordinary budgeting, use the bank’s available balance as a starting point, reconcile your own outstanding commitments, and preserve a practical cushion when possible. The current balance tells part of the account’s history. The usable amount depends on holds, pending items, and obligations that have not reached the bank yet.